

 02 9622 4888

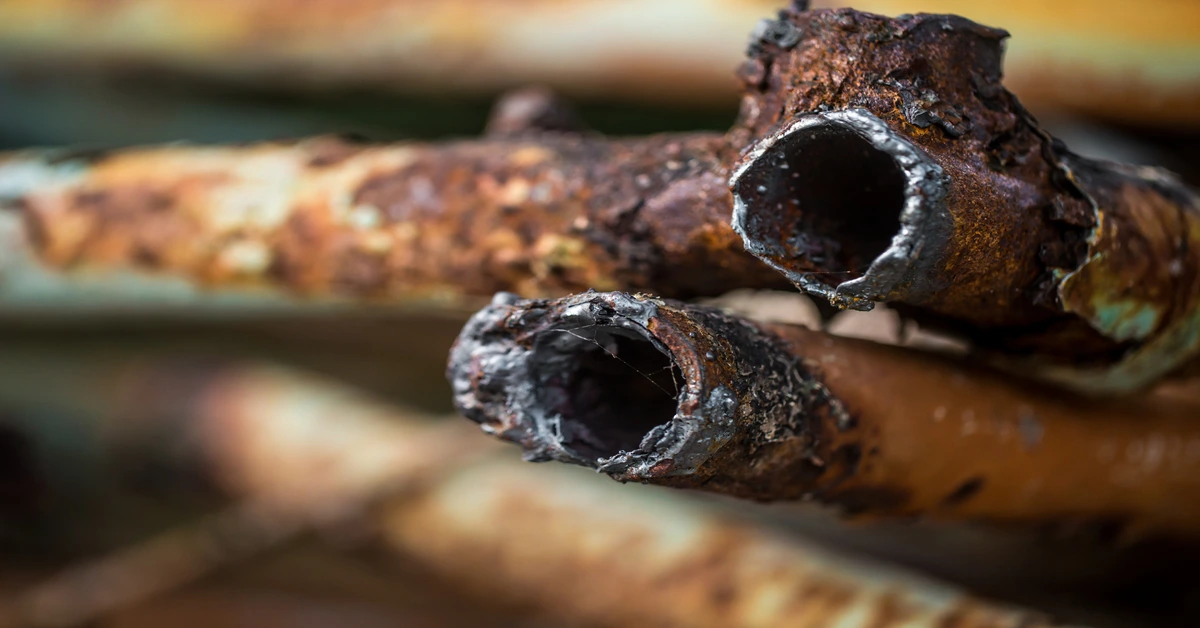
Most Sydney home insurance policies cover the damage a burst pipe causes — flooring, walls, ceilings, and belongings — but they generally do not cover the cost of repairing or replacing the pipe itself. Cover also depends on whether the burst was sudden and accidental, or the result of a slow leak you reasonably should have noticed. Insurers call this “escape of liquid” cover, and the fine print on gradual damage is where most Sydney homeowners get caught out.
A burst pipe doesn’t wait for a convenient time. It’s usually 2am, it’s usually spraying across the ceiling, and the first thing most homeowners think after shutting off the water is: will my insurance actually pay for this? The honest answer is — it depends on details most people never read until they’re filing a claim.
What “Escape of Liquid” Cover Actually Means
Every standard home and contents policy sold in Australia includes a clause insurers call escape of liquid (EOL). It’s the industry term for water, or another liquid, leaking out from where it’s meant to be contained — a burst pipe, a failed washing machine hose, an overflowing bath.
According to consumer group Choice, EOL claims have become one of the most common types of home insurance claims in Australia, with rising frequency and cost across the industry. That’s a strong signal this isn’t a rare event — it’s one of the most likely reasons a Sydney homeowner will ever file a claim.
Sudden Burst vs. Gradual Leak: The Difference That Decides Your Claim
This is the single biggest factor insurers weigh when assessing a burst pipe claim.
| Type of Damage | Typically Covered? | Why |
| Sudden, accidental pipe burst | Usually yes | Classed as an unforeseen event outside your control |
| Hidden gradual leak (undetectable) | Often yes, with conditions | Covered if a “reasonable person” wouldn’t have noticed it |
| Gradual leak you knew about or ignored | Usually no | Treated as a maintenance failure, not an accident |
| Cost to repair/replace the burst pipe itself | Rarely covered | Insurers cover resulting damage, not the faulty item |
| Pool or spa pipe leaks | Varies by insurer | Some exclude entirely; always check your PDS |
A sudden pipe burst — like a copper pipe splitting from age or a joint failing under pressure — is generally treated as accidental damage. A slow, hidden leak inside a wall cavity is a greyer area: many insurers will cover the resulting damage, but only if there’s no reasonable way you could have known about it beforehand.
Spotted a slow leak before it becomes a claim?
JG Wilson Emergency Plumbers can find and fix it fast.
Why Insurers Rarely Pay to Fix the Pipe Itself
This trips up a lot of homeowners. Insurance is designed to cover loss, not maintenance. So while your insurer will likely pay to replace water-damaged flooring, repaint ceilings, or repair a soaked timber subfloor, the actual pipe that burst is considered part of your property’s upkeep — and that repair cost sits with you.
This is exactly why proactive plumbing maintenance matters more in Sydney than people assume. A large share of older Sydney homes, particularly in the Blacktown and greater western Sydney corridor, still run on original copper or galvanised piping that’s well past its practical lifespan. Scheduling a general plumbing check-up before a pipe fails is almost always cheaper than the excess, the disruption, and the parts of the damage your policy won’t touch.
What This Means for Older Sydney Homes
- Homes built before the 1990s are more likely to have ageing metal pipework prone to corrosion-related bursts
- Corrosion-related failures are sometimes classified as “gradual” rather than “sudden,” which can affect your claim
- A periodic inspection through a residential plumbing service can catch corrosion before it becomes a burst pipe and an insurance dispute
Does Home Insurance Cover Water Damage From a Burst Flexible Hose?
Yes, generally — and it’s more common than most people realise. Burst flexi-hoses (the braided hoses connecting dishwashers, washing machines, and toilets) account for a meaningful share of all water damage claims nationally. Because a flexi-hose failure is almost always sudden and unexpected, it’s usually covered in the same way as a burst pipe. If you’re unsure of the difference between the two failure types and what it means for your home, our guide on [burst flexible hose vs burst pipe damage] breaks down how each one behaves and what to check around your appliances.
What to Do Immediately After a Pipe Bursts (Before You Call Your Insurer)
- Shut off the main water valve — this limits damage and shows the insurer you acted reasonably.
- Turn off electricity to any affected areas if water is near power points or fittings.
- Photograph everything — the pipe, the water damage, and the surrounding area, before any cleanup begins.
- Call a licensed emergency plumber to stop the leak and provide a written assessment — most insurers require this as supporting evidence.
- Contact your insurer promptly — most policies require notification within a set timeframe.
- Keep all invoices from plumbing repairs, water extraction, and temporary accommodation if needed.
Burst pipe right now?
Our emergency plumbers are on call 24/7 across Sydney. Call us today for an immediate response.
Why a Plumber’s Report Matters for Your Insurance Claim
Insurers don’t just take your word for it — most require documented proof that the damage was sudden and accidental, not the result of neglect. This is where a professional plumbing assessment becomes essential, not optional. A licensed emergency plumber can:
- Confirm whether the burst was sudden or the result of long-term deterioration
- Identify the exact failure point (joint, corrosion, water hammer, tree root damage, etc.)
- Provide a written report your insurer can use to process the claim faster
- Recommend immediate repairs to prevent further damage, which insurers expect you to carry out
Skipping this step is one of the most common reasons claims get delayed or partially denied — the insurer simply has no independent confirmation of what happened.
Common Reasons Burst Pipe Claims Get Rejected
- No evidence of sudden failure — the insurer suspects the leak was gradual and pre-existing
- Lack of maintenance — corroded, ageing pipework left unaddressed for years
- Unoccupied property — some policies limit cover if a home was vacant for an extended period when the burst occurred
- Pipe replacement claimed instead of damage repair — most policies won’t pay for the faulty pipe itself
- Delayed reporting — waiting too long to notify the insurer after discovering the damage
How JG Wilson Emergency Plumbers Can Help With Your Claim
When a pipe bursts, having a fast, well-documented response makes a real difference to how smoothly your insurance claim proceeds. JG Wilson Emergency Plumbers has served Sydney homeowners for over 30 years, providing 24/7 emergency callouts, detailed assessment reports, and same-day repairs — everything you need to support your claim while also getting your home back to normal quickly. If you’re dealing with a wider water pipe failure rather than a single burst point, our [water pipe repair] team can assess the full extent of the damage in one visit.
Need a plumbing report for your insurance claim?
Get a fast, documented assessment from JG Wilson Emergency Plumbers.
FAQs
Does home insurance cover a burst pipe in Sydney?
Generally, yes — most policies cover the water damage caused by a sudden, accidental pipe burst. They usually don’t cover the cost of repairing the pipe itself.
Will my insurance cover a slow, hidden leak?
Often, but only if the leak genuinely couldn’t have been noticed beforehand. If you knew about a drip or damp patch and didn’t act, the claim is more likely to be reduced or declined.
Does insurance pay to fix the actual burst pipe?
Usually not. Insurance typically covers the resulting damage — flooring, walls, belongings — not the faulty pipe or fitting that caused it.
Do I need a plumber’s report to make an insurance claim?
Most insurers expect one. A licensed plumber’s assessment confirms the cause and timing of the failure, which speeds up claim approval significantly.
Is water damage from a burst flexi-hose covered the same way as a burst pipe?
Yes. Flexi-hose failures are treated as sudden escape-of-liquid events in most policies, similar to a burst pipe.
What should I do first if a pipe bursts in my home?
Turn off your main water valve immediately, then call an emergency plumber to stop further damage before contacting your insurer.
A burst pipe is stressful enough without an insurance dispute on top of it.
JG Wilson Emergency Plumbers is available 24/7 across Sydney to stop the damage fast and provide the documentation your claim needs — Request a quote online today.

Comments are closed